From the 2023 Reform to the Tax Reality of 2026
In October 2023, Romania introduced one of the most significant revisions to its gambling industry’s tax and regulatory framework through Government Emergency Ordinance No. 82/2023.
The changes addressed licensing fees, operational authorization, responsible gambling contributions, and financial guarantee requirements.
Three years later, the original framework has been supplemented by additional fiscal and regulatory measures.
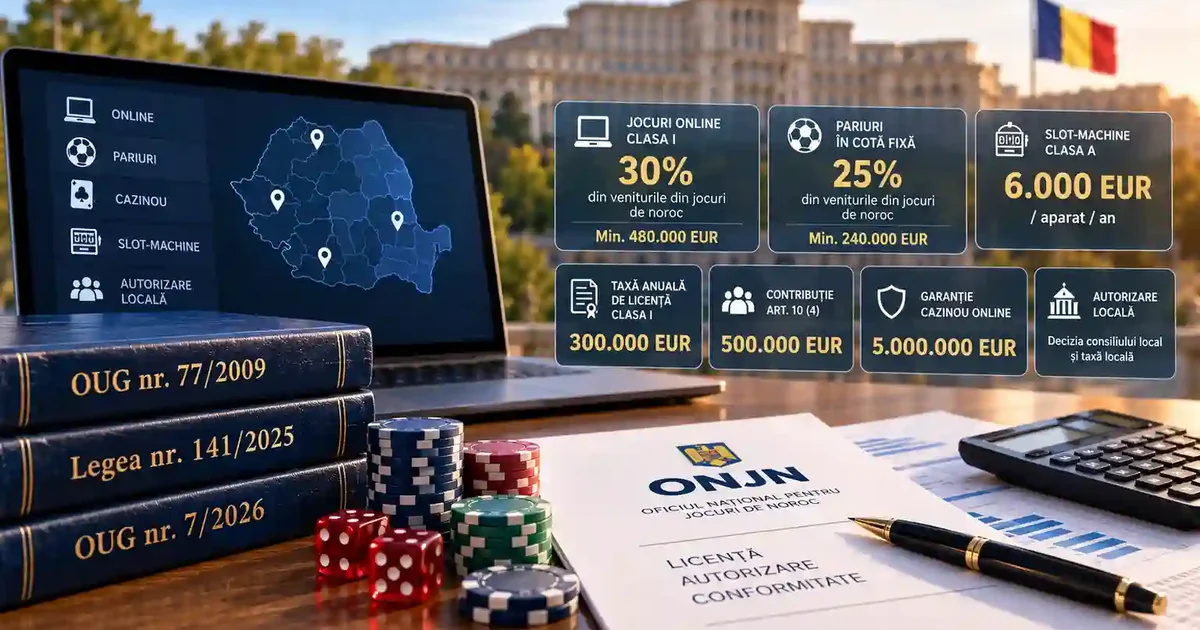
Law No. 141/2025 increased authorization fees for several gambling categories, including land-based betting, online gambling operators, and slot machines. These amendments became effective on August 1, 2025, and form the relevant tax framework for 2026.
Subsequently, GEO No. 7/2026 introduced an additional authorization layer for land-based gambling activities, granting local authorities significant powers over whether and where gambling premises may operate.
Consequently, the cost of operating a gambling business in Romania can no longer be assessed solely by reference to the ONJN licensing fee.
Operators must consider annual licensing fees, authorization fees, mandatory contributions, financial guarantees, administrative expenses, and, for land-based operations, local regulatory requirements. The overall regime is set out in our Romania gambling license guide.
In 2026, the relevant question for investors is not simply how much it costs to obtain a gambling license, but how much capital is required to establish and maintain a compliant and commercially sustainable operation.
1. Annual Gambling Licensing Fees in 2026
Licensing represents the first level of the regulated cost structure.
GEO No. 77/2009 establishes different annual licensing fees depending on the gambling activity. These fees are separate from the authorization fees payable for operating gambling activities.
Annual Licensing Fees by Category
| Gambling activity | Annual licensing fee |
|---|---|
| Online gambling – Class I (B2C) | EUR 300,000 |
| Related activities – Class II (B2B) | EUR 20,000 |
| Remote lottery gambling – Class III | EUR 200,000 |
| Land-based fixed-odds betting | EUR 200,000 |
| Pool betting | EUR 65,000 |
| Exchange betting | EUR 150,000 |
| Land-based casino games | EUR 150,000 |
| Land-based slot machines | EUR 150,000 |
| Poker clubs | EUR 25,000 |
| Bingo in gaming halls | EUR 15,000 |
Legal basis: GEO No. 77/2009, Annex, Section 1, Subsection I.
These amounts represent annual licensing costs for the specified categories. They do not include authorization fees, additional contributions, or financial guarantees.
For Class II licenses, the relevant activities are licensed separately under the applicable regulatory framework.
Companies providing software, gambling platforms, payment processing, or other regulated services should determine the correct classification of their activities before submitting a licensing application. Our Romania Class 2 (B2B) license guide covers the categories, the dossier and the timeline.
A Class II license should not be confused with authorization to organize gambling activities for players. B2B suppliers and B2C operators have different legal obligations and business models.
2. Authorization Fees: The Main Increases Applicable in 2026
The most significant difference compared with the 2023 framework concerns the fees associated with gambling operating authorizations.
Through Law No. 141/2025, Romania increased the rates applicable to several major gambling categories without making corresponding increases to all fixed licensing fees.
Authorization Fees Applicable in 2026
| Gambling activity | Annual authorization fee |
|---|---|
| Class I online gambling | 30% of GGR, minimum EUR 480,000 |
| Class III online gambling | 30% of GGR, minimum EUR 480,000 |
| Land-based fixed-odds betting | 25% of GGR, minimum EUR 240,000 |
| Land-based pool betting | 25% of GGR, minimum EUR 144,000 |
| Land-based exchange betting | 25% of GGR, minimum EUR 240,000 |
| Class A slot machines | EUR 6,000 per machine |
| Land-based casino, Bucharest | EUR 70,000 per gaming table |
| Land-based casino, outside Bucharest | EUR 40,000 per gaming table |
| Poker club, Bucharest | EUR 82,500 per location |
| Poker club, outside Bucharest | EUR 38,500 per location |
Legal basis: GEO No. 77/2009, Annex, Section 1, Subsection II, as amended by Article LXII of Law No. 141/2025.
For Class I online gambling operators, the increase from 21% to 30% significantly changes the industry’s cost structure.
The minimum annual authorization fee also increased from EUR 400,000 to EUR 480,000.
For land-based fixed-odds betting, the applicable rate increased from 21% to 25%, while the minimum annual fee rose from EUR 200,000 to EUR 240,000. Our analysis of sports betting taxation traces these rates back to 2020.
For Class A slot machines, the annual authorization fee increased from EUR 5,300 to EUR 6,000 per machine.
These amendments have been effective since August 1, 2025. The law also required adjustments to authorization fees for the remaining validity periods of authorizations already in force when the new rates became applicable.
What Qualifies as Gross Gaming Revenue?
Article 1¹ of GEO No. 77/2009 defines the relevant basis for calculating gambling authorization fees.
Generally, GGR represents the difference between the amounts collected from players as participation fees or stakes and the prizes awarded, including jackpots.
This measure is commonly referred to in the industry as Gross Gaming Revenue (GGR).
For gambling activities where the operator charges commissions to participants, the legislation establishes a separate method of determining the relevant revenue.
An important consideration for financial planning is that authorization fees are calculated using the gambling revenue defined by the sector-specific legislation, not the accounting profit remaining after salaries, marketing, rent, and technology expenses.
An operator may therefore generate positive GGR and incur substantial authorization fees even if its overall financial result is limited or negative.
3. What Does It Really Cost to Operate a Class I Online Gambling Business?
Understanding the economic impact requires separating fixed regulatory costs from obligations calculated according to the operator’s activity.
A Class I online gambling operator generally faces the following recurring obligations:
| Cost component | Annual amount |
|---|---|
| Class I licensing fee | EUR 300,000 |
| Contribution under Article 10(4) | EUR 500,000 |
| Minimum authorization fee | EUR 480,000 |
| Minimum total for these components | EUR 1,280,000 |
This amount is illustrative and applies to an operator whose gambling revenue does not result in an authorization fee exceeding the statutory minimum.
It excludes financial guarantees, initial administrative fees, technology expenses, marketing, professional services, general corporate taxes, and other applicable obligations. The full application route and a cost calculator are in our Romania Class 1 (B2C) license guide, and the corporate requirements in Romania Class 1 company formation.
Example: An Operator Generating EUR 4 Million in Annual GGR
For an operator generating EUR 4 million in annual GGR, the 30% authorization fee amounts to EUR 1.2 million.
Adding the EUR 300,000 annual licensing fee and the EUR 500,000 annual contribution results in total annual obligations of EUR 2 million for these three components.
This calculation illustrates the fiscal pressure on the business model but does not represent the operator’s total taxes and expenses.
The commercial implication is straightforward: a business model developed using the tax assumptions applicable in 2023 may produce significantly different operating margins in 2026.
Operators should update their financial forecasts using current rates, realistic business volumes, and both growth and downside scenarios.
4. Responsible Gambling Contributions and Other Special Taxes
In addition to licensing and authorization fees, GEO No. 77/2009 establishes annual contributions to finance the activities provided for under Article 10(4), including gambling addiction prevention and the protection of vulnerable groups.
These contributions are separate from authorization fees.
The main annual amounts applicable in 2026 include:
| Category | Annual contribution |
|---|---|
| Class I online operator | EUR 500,000 |
| Class II licensed supplier | EUR 15,000 |
| Class III online operator | EUR 100,000 |
| Land-based fixed-odds betting | EUR 200,000 |
| Pool betting | EUR 50,000 |
| Exchange betting | EUR 100,000 |
| Land-based casino games | EUR 4,000 per table |
| Poker clubs | EUR 5,000 per club |
| Slot machines | EUR 500 per machine |
For the first calendar year in which a license is granted, the contribution must generally be paid within 10 days of the approval of the licensing documentation. For subsequent years, the payment deadline is January 25.
Specific rules concerning the calculation and payment of contributions for individual slot machines apply from 2026, taking into account the authorization of each gaming device.
Vice Tax for Slot Machines and VLTs
Since August 1, 2025, the vice tax applicable to legally specified slot machines and video lottery terminals (VLTs) has been EUR 1,000 annually for each authorized gaming position, payable monthly in accordance with the statutory requirements.
For a Class A slot machine, the three principal regulatory charges directly associated with the gaming device are:
- EUR 6,000 annual authorization fee;
- EUR 500 annual contribution;
- EUR 1,000 annual vice tax.
The combined amount is EUR 7,500 per machine per year, before allocating the general licensing fee, financial guarantee costs, potential local taxes, and operating expenses.
Video lottery and lottery games are also subject to separate special taxes, including the 4.5% rate applicable to VLTs and the 8% rate applicable to lottery games other than video lottery, under the conditions set out in the statutory annex.
Gambling Advertising Tax
Article 1² of GEO No. 77/2009 also establishes an advertising tax of 5% of the value of certain advertising contracts.
Its scope covers the contracts defined by the law, including particular forms of advertising in public spaces and on television.
It should not automatically be interpreted as a 5% tax on all digital marketing expenses or the operator’s entire promotional budget.
The correct treatment depends on the contractual arrangements, the parties involved, and the specific advertising channels used. The fee was introduced by GO 15/2022; see how GO 15/2022 changed Romania’s gambling fees.
5. Financial Guarantees in 2026
Taxes and fees represent only part of the capital required to operate a gambling business.
Article 29 of GEO No. 77/2009 regulates the financial guarantees intended to cover the risk of non-payment of obligations to Romania’s consolidated public budget.
The fixed guarantee amounts effective from January 1, 2025, remain relevant in 2026.
| Gambling category | Required guarantee |
|---|---|
| Land-based gambling, excluding casinos | EUR 1,000,000 |
| Land-based casinos | EUR 3,000,000 |
| Online gambling, excluding online casinos | EUR 2,000,000 |
| Online casinos | EUR 5,000,000 |
These amounts should not be confused with annual taxes or fees.
A financial guarantee represents an obligation to secure fiscal risks and may be provided through instruments permitted by law, including bank guarantees and other forms specified under Article 29.
The amendments introduced by Law No. 141/2025 also addressed the conditions applicable to surety insurance policies.
From an investor’s perspective, this distinction matters.
A financial guarantee is not ordinarily a definitive tax expense, but it may involve committed capital, banking costs, collateral requirements, or the use of credit facilities.
An online operator planning to launch casino gaming must assess the EUR 5 million guarantee requirement separately from the budget allocated to licensing and authorization.
A gambling license may appear affordable in terms of annual licensing fees while remaining challenging to sustain from a capital and liquidity perspective.
6. The Major Regulatory Change in 2026: Local Authorization and Municipal Fees
Government Emergency Ordinance No. 7/2026, published in the Official Gazette No. 146 of February 25, 2026, introduced one of the most significant changes for land-based gambling operators.
Under the newly introduced Article 18¹ of GEO No. 77/2009, local councils have the authority to decide whether gambling activities may be conducted within their administrative territories.
Where such activities are permitted, operating gambling activities at physical premises is subject to obtaining an annual local authorization.
Local authorities may determine the areas where gambling activities are allowed and set the relevant local authorization fees based on the surface area of the premises where the activity is carried out.
The annual local fee must be paid within 30 days of the issuance of the operating authorization.
Transitional Rules for Existing Operators
GEO No. 7/2026 contains an important transitional provision for operators holding valid ONJN authorizations when the ordinance entered into force.
For these operators, the new local authorization requirements become applicable upon the expiry of their existing authorization period.
The local fee is not payable during the period protected by this transitional provision.
This distinction should be assessed individually for each location and authorization.
Implications for Land-Based Operators
In 2026, evaluating a gambling location involves more than customer traffic, rental costs, and commercial potential.
Before opening or continuing operations, operators must review the relevant local council decisions, authorization regulations, permitted zones, applicable fees, and the expiry dates of existing authorizations.
For slot machines, the requirement concerning their location in administrative-territorial units with a registered resident population exceeding 15,000 inhabitants also remains relevant, under the conditions of Article 15(2)(b¹).
A location that appears profitable from a commercial perspective may become unviable if it does not satisfy the applicable operating conditions or if the local authority decides not to permit gambling activities.
Operators managing extensive retail networks therefore need location-specific regulatory assessments rather than relying exclusively on consolidated financial forecasts at national level. The ordinance’s effect on slot halls is analyzed in OUG 7/2026 and Romania’s slot machines, and the local veto alongside the B2B renewal cycle in our 2026 regulation update.
7. Taxation of Players’ Gambling Winnings in 2026
The taxation of gambling operators must be distinguished from the personal income tax applicable to players’ winnings.
Law No. 141/2025 amended Article 110 of the Romanian Fiscal Code, introducing a new progressive tax schedule effective from August 1, 2025.
| Gross income received by the player | Applicable tax |
|---|---|
| Up to and including RON 10,000 | 4% |
| Above RON 10,000 and up to RON 66,750 | RON 400 + 20% of the amount exceeding RON 10,000 |
| Above RON 66,750 | RON 11,750 + 40% of the amount exceeding RON 66,750 |
For online gambling, tax is calculated and withheld at source when funds are transferred from the player’s gaming account to a bank account or similar account.
For winnings from games characteristic of casinos, poker clubs, slot machines, and scratch cards, the Fiscal Code provides a separate treatment, including a tax-free threshold of RON 66,750 and a specific calculation method for amounts exceeding that threshold.
From an operator’s perspective, the amendments require accurate configuration of tax calculation systems, reconciliation between payments and withheld taxes, and maintenance of the records necessary for fiscal reporting. The operator’s withholding and filing duties are covered in the obligations of bookmakers toward the Treasury and players.
From a player’s perspective, the revised tax rates affect the net amounts received.
Income paid from foreign sources requires a separate tax assessment and should not be confused with the final withholding-at-source regime applicable under Romanian legislation. Worked examples from the player’s side are in our Romanian guide, 5 întrebări despre impozitarea veniturilor din pariuri online.
8. Economic Impact: How the New Tax Structure Affects Business Models
The successive amendments introduced between 2023 and 2026 have changed how investments in Romania’s gambling industry should be evaluated. Market size and ONJN fee receipts are covered in our Romania gambling market in 2026 analysis, including the 2027 scenarios.
For online operators, the main pressure arises from the combination of the 30% GGR-based authorization fee, the fixed annual contribution, and financial guarantee requirements.
For land-based operators, costs are influenced not only by national taxes and fees but also by the number of gaming devices, the type of premises, and local authorization conditions.
For Class II suppliers, the EUR 20,000 annual licensing fee and the EUR 15,000 contribution should be evaluated alongside the technical and compliance obligations applicable to each licensed activity.
Amendments introduced through Law No. 141/2025 and Law No. 239/2025 have also introduced or adjusted specific responsibilities for certain categories of B2B suppliers serving online gambling operators. See Class II reporting obligations under Law 141/2025.
Operating Margins Must Be Recalculated
An increase in GGR does not automatically translate into a proportional increase in profit.
As revenue grows, the percentage-based authorization fee may exceed the statutory minimum.
Operators must also cover payment processing, marketing, platform infrastructure, staffing, security, and compliance expenses.
For a reliable financial model, regulatory taxes and fees should be assessed separately from operating expenses and financial guarantees.
In particular, capital committed to financial guarantees should not automatically be recorded as an annual expense, but it must be included in liquidity and financing assessments.
Competition Depends on More Than Tax Rates
A higher tax burden may favor established operators that already have the necessary infrastructure, access to financing, and a sufficiently large customer base to distribute fixed costs efficiently.
At the same time, financial and administrative barriers may reduce market attractiveness for certain business models or smaller operators.
For investors, the central question is whether the market’s size, revenue potential, and competitive advantages justify the combined cost structure and associated regulatory risks. For a cost comparison with other regimes, see gambling license costs in 2026, our jurisdictions register and the guide to starting an online casino in 2027.
9. Compliance Priorities for Gambling Operators in Romania
In 2026, effective tax management begins with correctly identifying the activities actually carried out by the business.
Finance, operations, legal, and compliance teams should apply a consistent classification of gambling products, authorizations, and gaming devices.
Operators should maintain a centralized register of regulatory obligations that links licenses, authorizations, contributions, guarantees, and payment deadlines.
For activities subject to revenue-based authorization fees, systems should support the reconciliation of GGR with technical reports, financial records, and tax returns.
For land-based premises, the register should also include local operating authorizations, municipal council decisions, and location-specific requirements.
For Class II suppliers, assessments should extend to the services actually provided, contractual relationships with operators, and the technical or reporting obligations associated with the relevant license.
Payment Deadlines Matter as Much as Tax Rates
Annual licensing fees, contributions under Article 10, authorization fees, and periodic tax obligations do not necessarily share the same payment deadlines.
For example, annual contributions provided under Article 10(4) are generally payable by January 25 for years following the granting of the license. Specific provisions apply to slot machines.
Revenue-based authorization fees are subject to the declaration, payment, and adjustment mechanisms established by Article 14, while certain fees associated with gaming devices are paid monthly.
For fees and guarantees denominated in euros, the RON equivalent is determined in accordance with the rule set out in the Annex to GEO No. 77/2009, using the relevant exchange rate published in the Official Journal of the European Union for the first working day of October of the year preceding the year in which the obligation becomes due.
An inadequately managed tax calendar can create costs and risks that extend beyond the amount of an overdue payment. The full monthly calendar is in the deadlines and taxes that keep your license alive.
10. Conclusion: Tax Compliance and Commercial Viability Must Be Assessed Together
Romania remains an important jurisdiction within the European gambling industry, but its tax and regulatory framework in 2026 is significantly more complex than the one examined in October 2023.
The increase in authorization fees under Law No. 141/2025, the continued application of substantial mandatory contributions and financial guarantees, and the introduction of local authorization requirements under GEO No. 7/2026 demand a more detailed assessment of both new projects and existing operations.
For online operators, sustainability depends on the relationship between GGR, recurring regulatory obligations, and the resources required to maintain compliance.
For land-based operators, commercial viability must be assessed at the individual location level, considering regulated costs and conditions imposed by local authorities.
For B2B suppliers, licensing costs should be assessed together with the nature of the licensed activities, technical responsibilities, and contractual obligations.
In 2026, a viable gambling business is not merely one that can obtain a license. It is one that can finance, demonstrate, and maintain compliance throughout its operations.
Advisory Support for Operators, Suppliers and Investors
Szilaghi Consulting provides advisory services covering gambling licensing and authorization in Romania, corporate structuring, tax compliance, and representation before the National Gambling Office (ONJN).
We assist operators and suppliers in evaluating market-entry requirements, regulatory costs, reporting obligations, and the impact of legislative developments on their business models.
For existing operators, our assistance may include reviewing current licensing and authorization structures, verifying tax obligations and financial guarantees, and assessing requirements applicable to individual locations.
For investors and new market entrants, the objective is to develop an operational model that reflects the actual cost of regulatory compliance before significant financial commitments are made.
For further information, explore our gambling consulting services or contact Szilaghi Consulting for an assessment of your project.
This article is provided for general informational purposes and does not constitute individualized legal or tax advice. Its application depends on the type of license, nature of the activity, gambling products offered, existing authorizations, and, where relevant, local regulations. Before relying on it for an investment decision, the consolidated legislation and applicable decisions of the competent authorities should be reviewed. Last legislative review: October 10, 2026.